FLSA vs. IRS Tests: Event Worker Classification
October 30, 2026

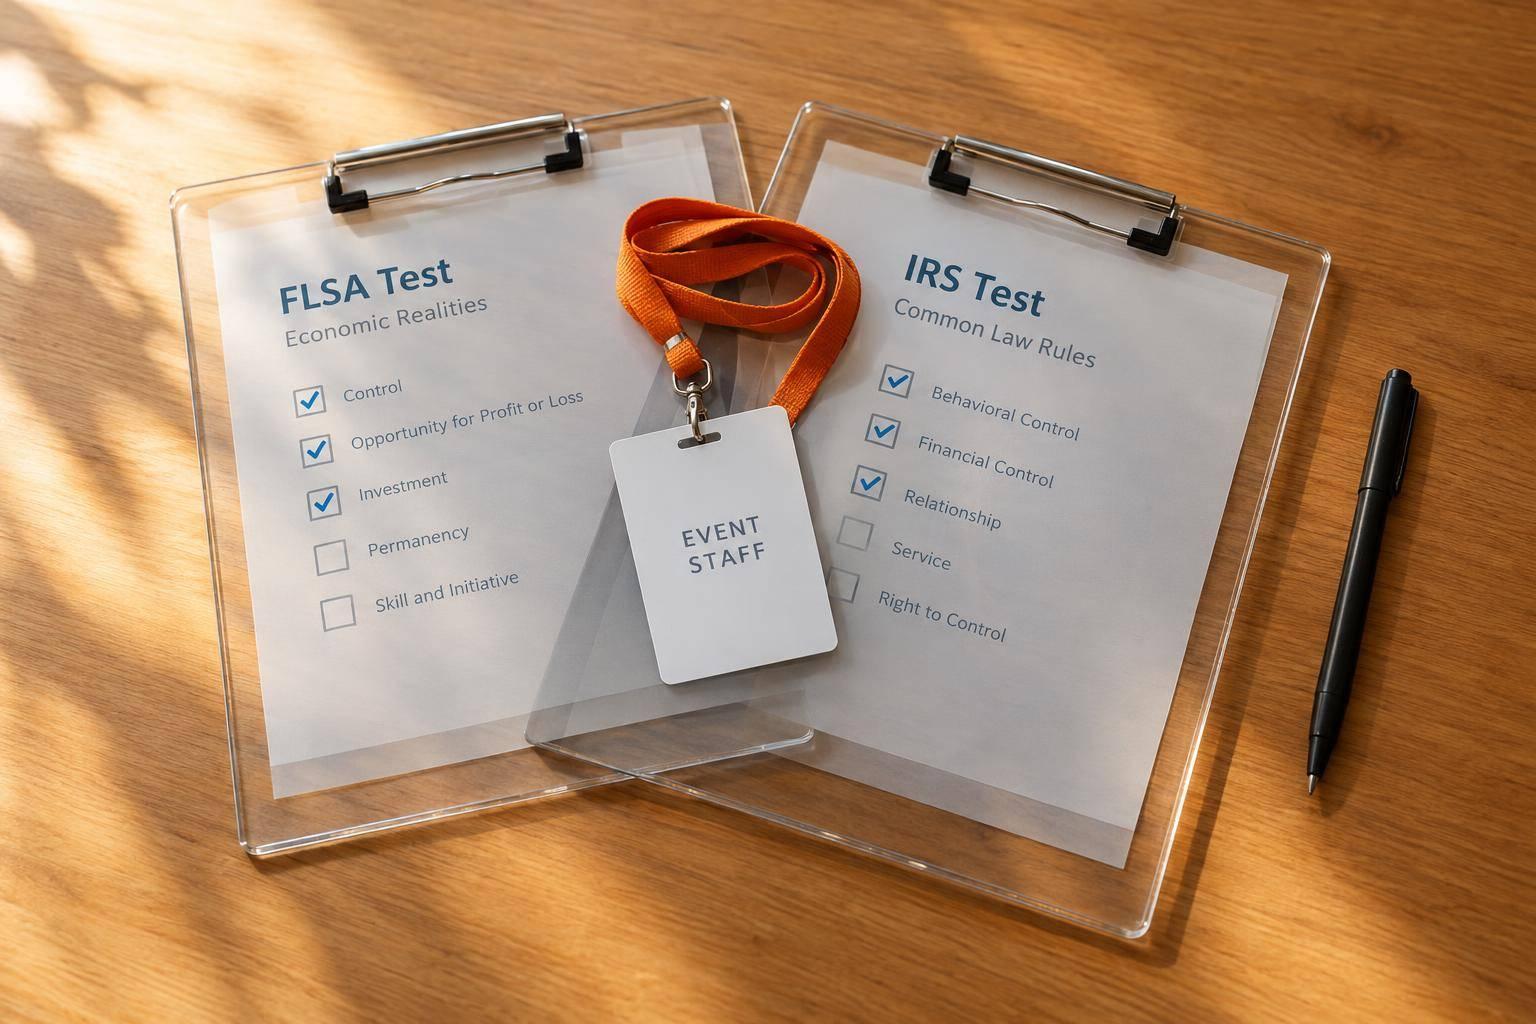
Event worker classification takes 2 separate reviews - not just a contractor agreement or a 1099-NEC. I start with the same schedules, pay terms, and supervision records, then apply each test separately.
Quick Comparison
| Comparison | FLSA | IRS |
|---|---|---|
| Main question | Economic dependence | Right to control the work |
| Duties at stake | Minimum wage, overtime, and recordkeeping | Employment taxes, withholding, and reporting |
| If status is unclear | Check controlling law with employment counsel | Consult tax counsel; consider Form SS-8 |
My takeaway: <u>document what happens in practice</u>. Check who sets shifts, directs workers, and controls pay - not just what the contract says. Then record each conclusion, check state and local rules, and revisit the review when working conditions change. A result under one test does not settle the other.

FLSA vs. IRS: Two Tests for Event Worker Classification
Employee status brings FLSA minimum-wage, overtime, and recordkeeping duties, subject to coverage and exemptions. Nonexempt employees must receive at least the applicable minimum wage, plus overtime at 1.5 times their regular rate for hours worked over 40 in a workweek. Employee status and exemption status are separate questions.
Use the current federal economic-reality rule, 29 C.F.R. § 795.110. Proposed changes do not control unless they become final and take effect. Apply the controlling law in the relevant jurisdiction.
The six factors look at:
No single factor controls. Weigh the whole relationship.
For event staffing, look closely at the agency’s direction. Who sets arrival times, uniforms, service procedures, breaks, and reporting lines? Who gives corrective instructions during events?
Uniforms and arrival times alone do not decide status. But detailed procedures and continued supervision point more strongly toward control. Recurring bookings can show a continuing relationship, even if each event lasts only a few hours. Freedom to work for others matters when workers can actually market their services and turn down assignments without penalty.
More shifts do not equal entrepreneurial profit. Check whether workers can negotiate prices, find customers, hire help, or manage costs that affect profit or loss. Compare their business investments with the agency’s resources. Also ask whether their labor is the service the agency sells.
Document both sides of the analysis, and consult counsel on close cases. Using budget-friendly staff scheduling tools for flexibility alone does not prove contractor status. The IRS asks a different question: who controls the work for tax purposes.
The IRS common-law test determines whether a worker is an employee or an independent contractor for federal employment-tax and income-tax withholding purposes. Employee status generally requires federal tax withholding, payroll taxes, and related deposits and reporting.
Review the same schedules, instructions, and supervision records, but apply the IRS test. The same work record can lead to a different result under the IRS test than under the FLSA.
For event staffing, behavioral control means looking at actual supervision and any right a party retains to direct how the work gets done. In staffing-agency arrangements, document each party’s authority over assignments, supervision, discipline, replacement, and reassignment.
Financial control includes investment, unreimbursed expenses, payment terms, services offered to other clients, and the opportunity for profit or loss.
Relationship factors include benefits, how long the relationship lasts, agreements, and whether the services are central to the business. Calling someone an independent contractor in a contract does not decide their status under the IRS test.
Either the agency or the worker can file Form SS-8, “Determination of Worker Status for Purposes of Federal Employment Taxes and Income Tax Withholding,” if federal tax status remains unclear. Include facts about control, pay, expenses, tools, benefits, contracts, and how the arrangement works in practice.
Filing does not pause existing tax obligations. Keep withholding, reporting, deposits, and payments current while the request is pending. Consult a qualified tax professional about disputed classifications or corrections.
An SS-8 determination addresses federal employment-tax treatment; it does not settle FLSA or state-law status.
The same facts face two different tests. FLSA focuses on economic dependence. The IRS focuses on the right to control the work for tax purposes.
The difference isn’t whether the facts exist. It’s how each test weighs them.
| Comparison | FLSA economic reality analysis | IRS common-law test |
|---|---|---|
| Agency | U.S. Department of Labor, Wage and Hour Division | Internal Revenue Service |
| Purpose | Federal minimum wage, overtime, and recordkeeping protections | Federal employment-tax, withholding, and reporting obligations |
| Question | Is the worker economically dependent on the business? | Does the business have the right to control how the work is done? |
| Factors | Profit or loss, investments, permanence, control, integral work, and skill or initiative | Behavioral control, financial control, and the parties’ relationship |
| If misclassified | Back wages, overtime, liquidated damages, recordkeeping violations, and penalties | Payroll-tax assessments, filing corrections, interest, penalties, and W-2 reporting |
For staffing agencies, the same workplace rule can point to economic dependence under FLSA and control under the IRS test. Each fact serves a different legal purpose.
| Event-staffing fact | FLSA relevance | IRS relevance |
|---|---|---|
| Agency-controlled schedules | Fixed shifts and limited ability to refuse work may suggest dependence. | Setting when and where work happens suggests behavioral control, especially with detailed supervision. |
| Mandatory training | Training on service methods or required conduct suggests control. | Instructions on procedures, scripts, and service methods indicate behavioral control. |
| Uniforms | Required uniforms may indicate agency control. | Specific attire and presentation requirements may support behavioral control. |
| Worker-provided equipment | Meaningful business investment supports independence; minor personal items carry less weight. | Substantial investment and unreimbursed expenses may support independence when they create an opportunity for profit or loss. |
| Multiple agency clients | Serving several agencies or customers may support business independence. | Marketing services and maintaining outside clients support independence. |
| Repeated assignments | Recurring assignments may suggest a continuing relationship. | Continuity and expectations of future work may support employee status. |
| Services central to event operations | Core event services may be integral to the agency’s business. | Services central to the agency’s regular business may support employee status. |
Weigh the full relationship, not isolated facts. Separate logistical, safety, and venue requirements from instructions about how workers perform services.
A contractor label doesn’t decide the result. Agencies need a documented review process - not a one-time label - to assess scheduling, supervision, and pay terms separately under FLSA wage-and-recordkeeping duties and IRS tax-and-reporting duties.
Document each finding. A contract label, 1099-NEC, or result under another law doesn’t settle either test. If both the agency and client direct the worker, review joint-control exposure separately.
Use the same facts for separate FLSA and IRS reviews.
Create a file for each role that identifies who contracts with, directs, and pays the worker. Complete a worksheet for each review, then check state and local rules where the work takes place. Cover wage-and-hour requirements, unemployment insurance, workers’ compensation, and paid sick leave. Record each conclusion, the facts behind it, and the review date.
Document who sets schedules, duties, supervision, breaks, and pay terms. Note whether workers can accept or reject assignments, then use scheduling records to check how these practices play out over time.
Keep contracts, schedules, availability records, and assignment records - including offers and acceptances. Also retain messages, training materials, time and pay records, invoices, reimbursements, equipment and uniform rules, insurance, and performance reviews.
Document what happens in practice, not just what the contract says. Contract labels do not control FLSA status. Organize the file around control, economic dependence, profit or loss, permanence, and outside business activity.
Quickstaff can bring event, assignment, availability, waitlist, reminder, and staff communication records into one place. Compare these records across events, alongside payroll data and on-site practices, to see how the arrangement works over time. Software records the facts; it does not determine worker status.
Refer unclear or conflicting findings to employment and tax counsel. Have a payroll specialist help put the resulting withholding, timekeeping, and reporting decisions into practice. For unresolved federal tax status, consider Form SS-8.
Review recurring roles at least annually as a process check. Reopen the file sooner if pay methods, supervision, training, scheduling, equipment requirements, work locations, or contracting parties change. Keep a change log and document who approved the updated FLSA and IRS conclusions.
The FLSA and IRS answer different questions. The FLSA asks whether a worker depends on the business economically. The IRS asks whether the business has the right to control the work for federal employment-tax purposes.
A contract label does not decide the outcome under either test. For IRS purposes, an agency’s right to control the work can matter even if it never uses that right.
For staffing agencies, this means reviewing each recurring event role under both frameworks, using records of how the work is actually done. Keep the facts that support each decision on file, and check state and local rules before acting. A result under one test does not settle every obligation.
The FLSA and IRS use different criteria to classify workers. Meeting one test doesn’t mean you meet the other. If a worker’s status is unclear, file Form SS-8 to request an IRS determination. That decision doesn’t automatically settle the worker’s status under the FLSA or state law.
If a worker was misclassified, consult a professional about possible back wages, tax reporting requirements, and overtime liability.
Yes. Your staffing agency and an event client can both be employers of the same worker, often as joint employers, if each has enough control over the worker’s schedule, tasks, or working conditions.
The FLSA’s economic reality analysis and the IRS’s common-law control and independence criteria look at the actual working relationship - not job labels or who pays the worker. Meeting one test doesn’t necessarily mean meeting the other, and both parties may share the risk of misclassification.
Review contracts, job duties, and the degree of control over independent contractors. Reclassify workers who should be employees and calculate any unpaid wages, overtime, or benefits owed.
Address tax issues by updating W-2 forms and paying employer Social Security, Medicare, and unemployment taxes. Consider filing Form 8952 to seek possible federal employment tax relief through the Voluntary Classification Settlement Program.
If a worker’s classification is still unclear, consider filing Form SS-8 for an IRS determination. That determination does not resolve classification under the FLSA.